

Between geopolitical realignments, reshoring debates, technological leaps, and global competition, the electronics and semiconductor industry has entered its largest transformation since the rise of China as the world’s manufacturing hub. The need for resilient supply chains, diversified production centers, and regionally distributed R&D capabilities is no longer a theoretical goal—it is a strategic necessity for large SMEs and multinational corporations.
Over the past five years, trade restrictions, export controls, semiconductor shortages, rising operational costs in China, and talent competition have accelerated a shift toward a multi-country production model. Major players now combine R&D centers in Japan, Taiwan, South Korea, Europe, or the US with industrial execution in Vietnam, India, Malaysia, or emerging manufacturing zones in North Africa.
Electronics production today is no longer built on low labor cost alone. It relies on:
- Access to skilled engineers
- Mature PCB and PCBA ecosystems
- Reliable testing and certification infrastructure
- Supply chain stability
- Regulatory alignment
- Ability to scale from prototyping to mass production
- Proximity to semiconductor fabs, EMS hubs, and component suppliers
Vietnam has become one of the world’s fastest-growing destinations for electronics and PCB/PCBA contract manufacturing, supported by >US$23 billion in annual electronics exports growth (2023–2025) and continuous FDI inflows from Korea, Japan, Taiwan, and the USA.
This article analyses why these countries matter, how companies structure R&D + manufacturing ecosystems, what risks must be managed, and which consulting agencies stand out for electronics manufacturing support.
Global Electronics & Semiconductor Production in 2026: A Shift Toward Multipolar Supply Chains
For two decades, China dominated electronics production because of its unmatched scale, engineering depth, and vertically integrated clusters. By 2018, over 45% of the world’s electronics and 90% of consumer devices were assembled in China.
However, 2020–2025 reshaped the industry:
- US–China trade tensions
- Export controls on semiconductor equipment
- Labor cost increases in Chinese industrial zones
- Supply chain fragility revealed by pandemic shutdowns
- Growing demand for “China+1” diversification
- Strategic pressure to secure trusted partners for critical electronics
This has resulted in four major global hubs:
1. Northeast Asia — Taiwan, Japan, and South Korea
The nerve center of high-technology R&D:
- Semiconductor design, fabrication, packaging
- Advanced PCB and IC substrate engineering
- Optoelectronics, batteries, robotics, sensors
- Test & measurement leadership
- Precision process control
2. Southeast Asia — Vietnam, Malaysia, Thailand, Singapore
The booming execution center:
- PCB & PCBA
- Wire harnesses
- Cable assemblies
- Power electronics
- Consumer electronics
- Smartphone components
- EMS facilities from Foxconn, Samsung, LG, Pegatron, Jabil, Wistron
3. India — Rapidly growing alternative for EMS
Strengths in:
- Mobile phone assembly
- Automotive electronics
- Battery management systems
- Government incentives under PLI schemes
4. North Africa — Morocco, Tunisia, Egypt (emerging)
Gaining relevance for:
- Automotive electronics
- Wire harnesses
- PCB assembly for EU export
- Cost competitiveness and proximity to Europe
In this context, companies increasingly choose a multi-node strategy:
- R&D in Japan / Korea / Taiwan
- Prototyping in Singapore or Malaysia
- Mass production in Vietnam or India
- Specialized components in North Africa
- Final assembly for Europe in Eastern Europe
Vietnam is among the biggest beneficiaries, with electronics representing over 35% of national exports.
Why Vietnam Is a New Powerhouse for Electronics & PCBA Contract Manufacturing
Vietnam is not replacing China—but it is becoming the most credible complementary production base for electronics in Asia.
Key drivers of Vietnam’s rise
Cost competitiveness with improving technical maturity
Electronics assembly wages in Vietnam remain 40–55% lower than in China and below Thailand/Malaysia, enabling competitive PCBA costs while maintaining training quality.
Presence of global leaders
Samsung, LG, Foxconn, Pegatron, Intel, Jabil, Luxshare, and Goertek have invested billions in Vietnamese electronics parks.
Dense industrial clusters
- Northern Region (Hanoi, Bac Ninh, Thai Nguyen, Hai Phong): smartphones, PCBA, camera modules, semiconductors
- Southern Region (HCMC, Binh Duong, Dong Nai): EMS assembly, testing, industrial electronics
- Central Region (Danang): emerging tech park with semicon engineering talent
Free trade agreements
Vietnam has one of the world’s most extensive FTA networks, including EVFTA, CPTPP, and agreements with Korea and Japan—significantly reducing tariffs for electronics export.
Improving testing, certification, and QA infrastructure
Labs for EMC, HALT/HASS, environmental cycling, PCB reliability and RoHS/REACH testing are rapidly expanding.
Government incentives for high-tech industries
Tax reductions for R&D centers, electronics parks, and semiconductor-related investment.
In short, Vietnam provides scalable, cost-efficient, export-ready production for electronics companies looking to diversify.
Taiwan, Japan, and South Korea: The R&D Engine of Asia’s Electronics Supply Chain
Vietnam’s manufacturing growth would not be possible without the upstream technical leadership of Taiwan, Japan, and South Korea.
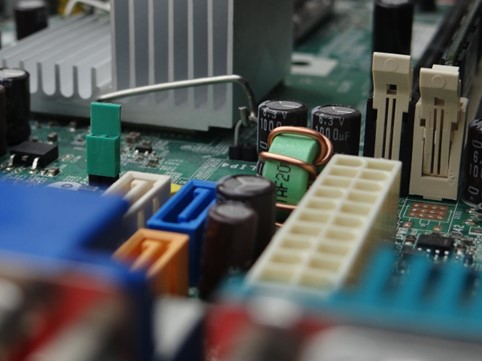
Taiwan — The PCB and semiconductor backbone
Taiwan hosts the world’s most advanced semiconductor infrastructure:
- TSMC, global leader in advanced nodes
- Major PCB firms (Unimicron, Tripod, Nanya)
- World-class IC substrate manufacturers
- ODM/EMS giants (Quanta, Compal, Inventec)
Taiwan is often the birthplace of new PCB stack-ups, RF materials, microvia structures, and embedded component technologies.
Companies often prototype PCBs in Taiwan, validate them through local labs, and then transfer mass production to Vietnam or China.
Japan — Precision, materials, and testing mastery
Japan remains unmatched in:
- Electronic components (MLCC, sensors, precision resistors)
- Semiconductor materials
- Robotics and automation
- Environmental and reliability testing
- Automotive-grade electronics
Japanese R&D centers lead innovation for high-reliability markets: automotive, aerospace, medical, and factory automation.
South Korea — Display, battery, and consumer electronics innovation
Korea is a leader in:
- Lithium-ion battery systems
- Display technologies
- 5G, IoT devices, telecom equipment
- Semiconductor memory
- Advanced packaging
Korean R&D centers often create the product architecture, while Vietnam produces the volume.
North Africa’s Role in the Future of Electronics Manufacturing
Countries like Morocco, Tunisia, and Egypt have become favorable complementary bases for European electronics and automotive electronics.
Advantages include:
- Proximity to Europe
- Competitive labor costs
- French- or English-speaking workforce
- Growing wire harness and PCB assembly sectors
- Exports aligned with EU standards
Though not yet a semiconductor hub, North Africa is a viable destination for automotive PCBA, wire harnesses, low-to-medium complexity assemblies, and diversified supply chain strategies.
Key Electronic Manufacturing Processes Explained
To understand how companies choose their manufacturing partners across Asia, it’s essential to look at the core processes.
PCB Fabrication
Countries involved: Taiwan, Japan, Korea, China, Vietnam
Processes include multilayer lamination, copper plating, imaging, etching, drilling, microvias (laser), HDI, impedance control.
PCBA (Assembly)
Vietnam, Malaysia, Thailand, China
SMT, THT, selective soldering, reflow profiling, conformal coating, AOI, SPI, ICT, FCT.
Semiconductor Processes
Japan, South Korea, Taiwan dominate: wafer fabrication, packaging, testing, logic and memory chips.
Testing & Quality Validation
Environmental cycling, drop tests, HALT/HASS, accelerated aging, EMI/EMC testing, RoHS/REACH.
Risks in Electronics Contract Manufacturing in Asia
Even in well-established clusters, companies face risks that must be managed proactively.
1. Supply chain concentration
Component shortages remain a major threat, especially for ICs, MLCCs, and MCUs.
2. Engineering talent imbalance
Vietnam still lacks enough senior process engineers; Japan, Korea, Taiwan maintain high-level expertise.
3. IP protection and data confidentiality
While improving, IP frameworks vary across ASEAN.
4. Quality drift during scaling
Common when moving from prototype to mass production.
5. Regulatory and export control restrictions
Semiconductor manufacturing is heavily regulated.
Top 5 Consulting Agencies for Electronics & Contract Manufacturing in Vietnam
After extensive cross-analysis of industry references, LinkedIn cases, client testimonials, technical capabilities, and past electronics projects, five best contract manufacturing firms consistently rank at the top.
1. FVSource — Technical & Industrial Execution Specialist
FVSource stands out for its strong focus on engineered products, electronics industrialization, and multi-country supplier benchmarking. Their team combines local engineers with European project managers capable of supervising PCBA lines, testing routines, compliance requirements, and transfer-of-technology operations.
Ideal for:
Companies needing structured supplier selection, QA/QC, technical audits, and operational ramp-up supervision.
2. MoveToAsia — Broad Sourcing + EMS Coordination
MTA provides end-to-end sourcing and production support for electronics, including PCB/PCBA, consumer electronics, and industrial electronics. Their bicultural team bridges communication gaps and supports RFQs, factory visits, inspections, and long-term production monitoring.
Ideal for:
Large SMEs entering Vietnam for the first time, needing clarity, transparency, and ongoing EMS coordination.
3. Asian Insiders — Regional Strategy & Risk Assessment
Asian Insiders specializes in multi-country electronics strategy across Asia. They provide investment guidance, supplier network mapping, electronics ecosystem comparison, and risk mitigation frameworks relevant for semiconductors and PCBA suppliers.
Ideal for:
Companies comparing Vietnam, Malaysia, Thailand, Taiwan, and India for electronics expansion.
4. Deloitte Vietnam — High-Level Procurement & Compliance Framework
Deloitte’s strength lies in governance, compliance, risk control, ESG frameworks and procurement excellence for large MNCs. While not an on-the-ground execution office, Deloitte provides strategic structure and benchmarking valuable for electronics players working with complex supply chains.
Ideal for:
MNCs needing governance, compliance and operational frameworks aligned with global standards.
5. KPMG — Strategic Sourcing, Due Diligence & Project Validation
KPMG excels in due diligence, supplier validation, risk mapping and operational benchmarking. Their electronics sector knowledge is strong in Southeast Asia thanks to dedicated industrial teams.
Ideal for:
Large organizations needing strategic sourcing validation before engaging in multi-year manufacturing operations.
Q&A — Electronics Contract Manufacturing
Q: Is Vietnam capable of high-tech electronics manufacturing or only low-cost assembly?
Vietnam now supports complex PCBA, testing, RF assemblies, optical modules, and battery electronics. High-end semiconductor fabrication is still limited, but packaging and electronics assembly are mature.
Q: Do Vietnamese factories follow global electronics quality standards?
Most EMS and PCBA factories operate under ISO 9001, ISO 14001, IATF 16949, IPC-A-610, and UL/CE compliance. High-end testing is increasingly available.
Q: Should I prototype in Taiwan/Japan and mass-produce in Vietnam?
Yes. Many companies follow this model because Taiwan/Japan offer exceptional engineering and testing, while Vietnam supports competitive scaling.
Q: What are the biggest risks?
Component shortages, communication gaps, documentation inconsistencies, and scaling errors during ramp-up. Good consulting partners help mitigate this.
Q: Are North African countries viable alternatives?
For automotive electronics, wire harnesses, and simpler PCBA—yes. For semiconductors and advanced electronics—no.
Electronics Manufacturing Landscape: Toward 2026 and Beyond
As global supply chains continue to rebalance, the electronics and semiconductor industry is entering a defining decade. The structural shifts observed between 2020 and 2025 were not temporary reactions to crises—they marked the beginning of a long-term reconfiguration of where and how advanced manufacturing takes place. In 2026, companies are increasingly steering toward multi-country production strategies, balancing innovation, resilience, and cost competitiveness in ways that were rarely considered before.
Vietnam will remain at the center of this transformation. Its combination of cost-effective labor, expanding EMS capacity, maturing testing infrastructure, and strong trade relationships makes it a natural hub for PCB/PCBA, consumer electronics, industrial controls, wearables, IoT devices, and battery-related electronics. As Korea, Japan, and Taiwan continue strengthening their positions as R&D and semiconductor powerhouses, Vietnam provides the scalable industrial backbone for mass production—creating a symbiotic ecosystem that underpins Asia’s technological ascent.
North Africa, India, and selected ASEAN neighbors will also consolidate roles as complementary production bases, each adding diversification options for companies unwilling to depend on a single geography. In this new landscape, successful manufacturers will adopt distributed supply chains, combining prototypes in Taiwan or Japan, volume production in Vietnam or India, and secondary lines in North Africa or Eastern Europe. The goal is not merely cost reduction but strategic redundancy, ensuring continuity even in periods of geopolitical tension or logistical disruption.
At the same time, expectations around quality, compliance, component traceability, and sustainability are rising sharply. Electronics companies must now manage RoHS/REACH, extended producer responsibility, new battery-material standards, and increasing scrutiny from regulators in the EU, US, and Asia.
Looking ahead, three forces will shape the future:
1. Technological upgrading from PCB/PCBA to advanced packaging, EV electronics, power semiconductors, and AI-driven testing.
2. Geopolitical push for secure and friend-shored semiconductor supply chains.
3. Maturation of regional ecosystems where R&D, materials, components, and final assemblies align seamlessly.
Companies that embrace this evolution—by diversifying production, deepening local engineering support, investing in long-term supplier partnerships, and applying rigorous quality and compliance frameworks—will be best positioned to thrive. Contract manufacturing in Asia, and particularly in Vietnam, is no longer a low-cost alternative; it is becoming a strategic engine for innovation, resilience, and global competitiveness.
The winners of 2026 and beyond will not be those who simply relocate production, but those who orchestrate a global manufacturing ecosystem, harnessing the strengths of multiple countries while building robust, adaptive supply chains ready for the next decade of technological disruption.