
Shopping for a mortgage on your own sounds simple enough until you actually start comparing lenders and realize how much the fine print varies from one offer to the next. This is usually where quebec mortgage brokers come into the conversation, since they do the legwork of pulling options from multiple lenders instead of leaving a buyer stuck with whatever their regular bank happens to be offering that month. A broker looks at income, credit, down payment size, and even future plans before recommending anything, which is a lot more thorough than a quick chat at a bank branch. Once people actually understand how a mortgage comparison works, it becomes pretty obvious why skipping that step tends to leave money on the table. Buyers who’ve been through the process a couple times already know that going in without comparing anything rarely ends up being the cheaper route.
Why Buyers Across Quebec Turn To Brokers Instead Of A Single Bank
Sticking with one bank feels easy, mostly because it’s familiar, but familiar doesn’t automatically mean the best deal. A bank can only pitch its own products, while quebec mortgage brokers work across a wider network and can actually shop an application around to see what else is realistically available. That gap matters more than people expect, since two lenders looking at the same borrower can come back with noticeably different rates and conditions. Brokers also tend to know which lenders move faster during busy seasons or handle certain income situations more flexibly than others. Buyers who’ve compared both routes side by side usually say the broker route felt less like guesswork and more like an actual negotiation over real numbers.
How Quebec Mortgage Brokers Handle Trickier Financial Situations
Not everyone’s file fits neatly into a standard checklist, and that’s exactly where a broker’s experience tends to show. Self employed buyers, people with irregular income, or anyone carrying a bit of bruised credit history often get turned away by traditional lenders who only look at things one narrow way. Quebec mortgage brokers who’ve seen these situations before know how to package an application so it highlights actual financial strength rather than just the messy bits sitting there on paper. They also know which lenders realistically say yes to non traditional income, saving buyers from wasting weeks applying somewhere that was never going to approve them anyway. This kind of problem solving genuinely matters for anyone whose finances don’t fit a simple box.
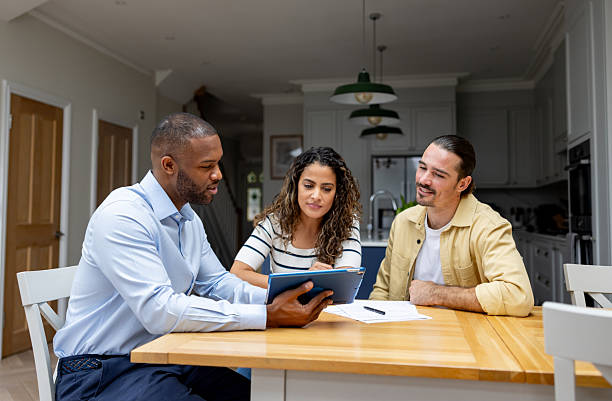
What A First Meeting With Quebec Mortgage Brokers Usually Looks Like
That first conversation typically sets the tone for everything after, and it usually starts with questions rather than a sales pitch. Good quebec mortgage brokers ask about income, existing debts, savings, and future plans before recommending anything, since jumping straight to a product without the full picture rarely leads anywhere useful. Buyers should show up with recent pay stubs, tax documents, and bank statements so that first meeting actually gets somewhere instead of turning into a vague chat about hopes and budgets. A decent broker also explains things in plain language, breaking down amortization and penalty clauses without assuming everyone already speaks fluent mortgage. If someone leaves that meeting more confused than when they walked in, that’s usually a sign they haven’t found the right fit yet.
Local Knowledge Sets Quebec Mortgage Brokers Apart From Generic Comparison Sites
Every region has its own quirks, and Quebec has plenty, from welcome tax calculations that catch new buyers off guard to specific rules around condo financing that vary from one municipality to another. Quebec mortgage brokers who actually work these markets day to day have usually dealt with these exact headaches before and know how to steer around them without wasting anyone’s time. Someone familiar with a specific city or neighbourhood knows which lenders get picky about older buildings and which ones move fast during a busy season. That kind of local familiarity doesn’t come from a generic online rate calculator, it comes from being in the trenches with real buyers, deal after deal, year after year.
Questions Worth Asking Before Choosing Among Quebec Mortgage Brokers
Before committing to anyone, it’s worth asking a few direct questions instead of just going with whoever answered fastest. How many lenders do they actually work with, or are they mostly tied to just one or two? How do they get paid, and does that shape which lenders they tend to steer people toward? How reachable will they be during closing if something unexpected comes up right before signing? Trustworthy housing market Montreal won’t dodge these questions or mumble through vague answers, and honestly, how someone reacts to being pushed a little upfront tells you a lot about how they’ll handle things later if a problem pops up.
Conclusion
Understanding rates and lenders is only half the picture, since keeping an eye on the housing market Montreal buyers are dealing with matters just as much when timing a purchase or a renewal. Prices shift, inventory disappears fast, and the housing market montreal can feel unpredictable without someone tracking it closely on a regular basis. Best Mortgage Montreal works with buyers trying to make sense of both sides of this, the financing details and the bigger picture of where the market’s actually heading, so decisions aren’t made on guesswork alone. Whether someone’s buying their first place or comparing options for a renewal, having the right person in their corner tends to make the whole process feel a lot less overwhelming.
FAQs
Do I have to pay a mortgage broker directly?
Usually not, since brokers are typically paid by the lender once the mortgage closes, so most buyers don’t see a direct fee for the advice they get.
Is it worth using a broker if I already like my current bank?
It’s still worth comparing, since a broker can shop your application across several lenders and might turn up better terms than your bank’s standard offer.
Can a broker help someone who’s self-employed?
Yes, brokers often know which lenders are more flexible with non traditional income and can package an application that highlights real financial strength.